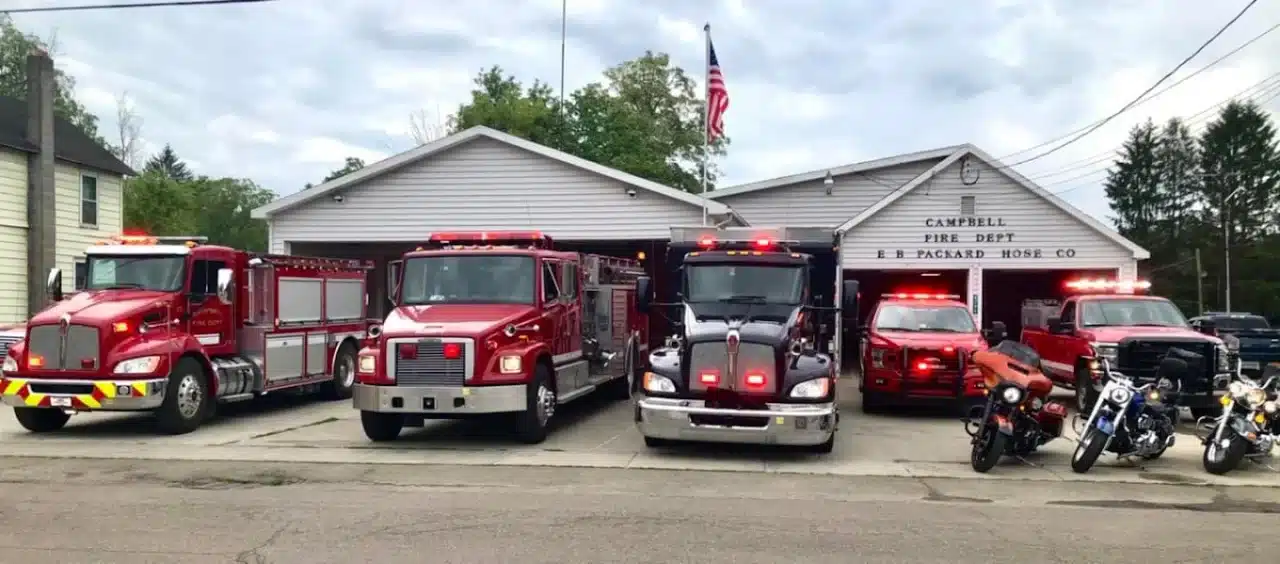
Campbell Fire Department could not document whether more than $31,000 in payments were appropriate, and tens of thousands of dollars were spent without required approvals, according to a state audit that found widespread weaknesses in the volunteer department’s financial oversight.
The state comptroller’s audit, issued Oct. 30, found that the department’s board and membership did not enforce financial requirements in their own bylaws. That left officials without reliable information to determine whether all money collected was deposited and whether spending served department purposes.
Department officials agreed with the findings and said they were developing a corrective action plan.
The nonprofit department has about 30 active volunteer members and provides fire protection and emergency services within Campbell Fire District No. 1 in Steuben County.
The audit covered Jan. 1, 2024, through June 15, 2026. Three people served as treasurer during that period. Financial transactions examined through Feb. 27, 2026, included $74,502 in deposited revenue and $76,298 in spending.
Payments lacked records and approval
Auditors examined 74 payments totaling nearly $49,000 and found that 41, totaling $31,053, lacked adequate supporting documentation, such as itemized invoices or receipts.
Without those records, auditors could not determine whether the payments were appropriate.
They also found that 58 payments totaling $45,847 were made without properly completed vouchers and advance approval from the board and membership. None of the 74 payments appeared in the required monthly treasurer reports.
The findings concern overlapping groups of payments within the same sample; the dollar amounts represent different problems rather than separate losses.
The department’s bylaws require the treasurer to pay bills after the board and membership approve completed vouchers. Instead, a former president and other members also used the department’s debit card to make purchases without the required approval process.
Auditors selected payments from five months based on spending levels and to include each treasurer’s tenure. The sample was not intended to represent every department transaction.
The report identified an increased risk of fraud, waste, abuse and loss. It did not establish that the undocumented payments involved theft.
Money from 2024 remained undeposited
Auditors also found weaknesses in how the department handled money from fundraising, pool fillings and hall and equipment rentals.
Members placed some collections in a locked filing cabinet, but officials could not identify everyone who had a key. The vice president generally collected and deposited hall rental payments while holding security deposits to return after events.
Although the current president told auditors Feb. 23, 2026, that no cash was on hand, a former president subsequently found $650 in undeposited funds from 2024 while gathering records.
That included $450 in cash and an outdated $200 check. The former president deposited the cash Feb. 26.
Financial records were also incomplete across the three treasurers’ terms. One former treasurer said she maintained a spreadsheet on a personal laptop but no longer had the computer and had not provided the department with an electronic copy. Another did not record financial transactions.
The current treasurer maintained computerized records, but auditors found errors in revenue classifications and bank reconciliations. Some checks were listed as outstanding even after clearing the bank, and eight required monthly reports were not provided.
Department agrees to strengthen oversight
The board did not conduct required quarterly audits between Jan. 1, 2024, and June 5, 2026. An outside annual audit required by the bylaws also was not performed during the audit period.
The comptroller made seven recommendations, including documenting all collections, obtaining approval before payments, providing detailed monthly reports and reviewing bank reconciliations. The board was also urged to conduct quarterly audits and arrange annual outside audits.
In an Oct. 23 response included in the report, volunteer treasurer and bookkeeper Kelly H. Fitzpatrick acknowledged the problems.
“We recognize the audit findings and agree with those findings,” Fitzpatrick wrote. “As the organization grew and changed, our policies and bylaws did not change in response to that growth.”
She said a corrective action plan was already being developed.
The comptroller encouraged the board to submit that plan within 90 days and make it available for public review.

FingerLakes1.com is the region’s leading all-digital news publication. The company was founded in 1998 and has been keeping residents informed for more than two decades. Have a lead? Send it to news@fingerlakes1.com.