Americans saving for retirement can contribute more to their 401(k) accounts in 2025, as the IRS has raised the elective deferral limit to $23,500, up from $23,000 in 2024. But the bigger story may be how President Trump’s newly signed One Big Beautiful Bill Act is transforming the retirement landscape—bringing both expanded benefits and heightened uncertainty for older savers.
2025 retirement contribution limits at a glance
According to IRS Notice 2024-80, the new 401(k) thresholds for 2025 are as follows:
- 401(k), 403(b), and 457 plans:
- Employee contribution limit: $23,500
- Catch-up for age 50+: $7,500
- Total possible contribution (50+): $31,000
- Higher catch-up for ages 60–63:
- Special catch-up: $11,250
- Total possible contribution: $34,750
- Traditional IRA limit: $7,000 (unchanged)
- IRA catch-up (50+): $1,000
- SIMPLE IRA limit: $16,500
- SIMPLE catch-up (50+): $3,500
- SIMPLE special catch-up (60–63): $5,250
The Big Beautiful Bill shakes up retirement strategy
Signed into law on July 4, 2025, the One Big Beautiful Bill Act (OBBBA) brings sweeping fiscal reforms with wide-reaching implications for retirees, especially those relying on tax-advantaged retirement accounts.
1. RMD rules may expand to Roths and large 401(k)s
While the bill does not change the SECURE 2.0-mandated glide path raising the Required Minimum Distribution (RMD) age to 75, it directs the Treasury Department to explore RMDs for Roth IRAs and large 401(k) balances. This signals a potential future shift in how tax-free retirement accounts are treated—raising concern among those who rely on Roth compounding.
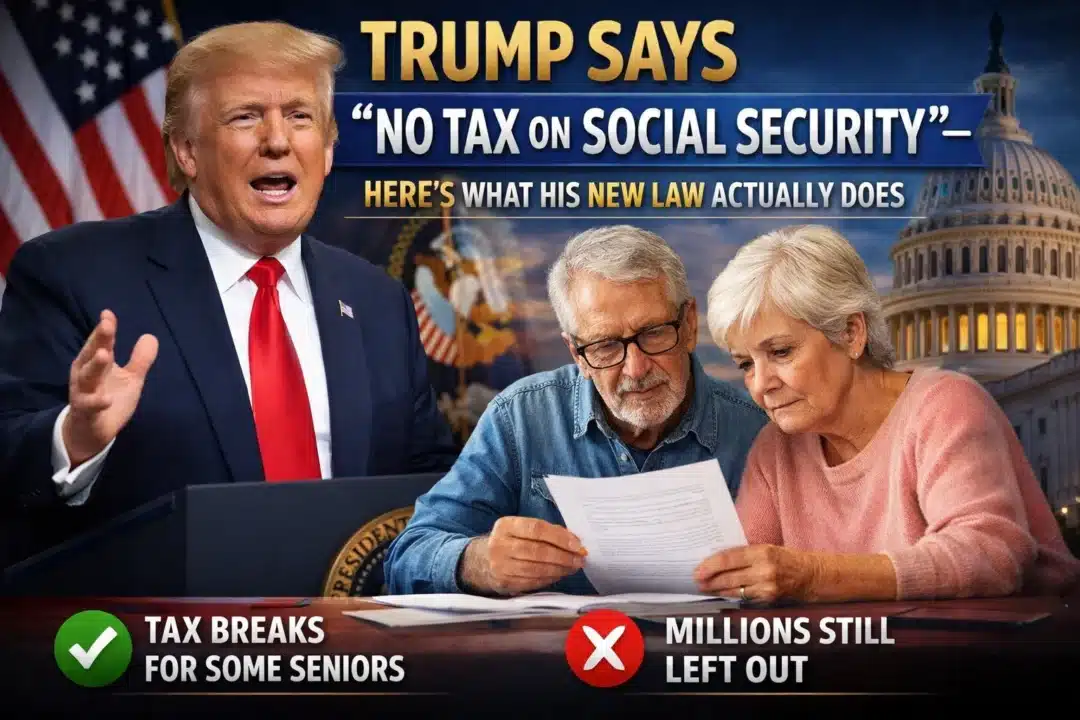
2. No elimination of taxes on Social Security—but a deduction helps
Despite campaign promises, OBBBA does not fully eliminate federal tax on Social Security benefits. Instead, it introduces a new “Senior Deduction”:
- $6,000 extra for single filers age 65+
- $12,000 for married couples age 65+
- Phases out at $75,000/$150,000 income
- Expires after 2028
According to the White House, nearly 88% of beneficiaries could now owe no federal tax on their Social Security income.
3. Estate tax exemption jumps to $15 million
Starting in 2026, the federal gift-and-estate tax exemption rises to $15 million per person or $30 million per couple, up from $13.99 million in 2025. The change is permanent in statute, though future Congresses could revisit it.
4. 529 account flexibility expands
OBBBA expands what qualifies under 529 plans, including:
- K-12 tutoring
- Caregiving certifications
- Rollover protections to Roth IRAs
This reduces penalties and expands education-related planning options for grandparents and retirees.
5. Medicaid and ACA subsidies face deep cuts
To offset tax breaks, OBBBA slashes over $1 trillion from Medicaid and Affordable Care Act subsidies. Though Medicare is untouched, states will be required to impose stricter asset-verification by 2026, complicating long-term care eligibility for older adults.
6. Most OBBBA tax perks sunset in 2028
The new deductions and middle-class credits introduced by the bill are temporary. Key benefits, including the senior deduction and tip-income exclusions, expire after 2028.
Planning outlook: What retirees should do now
Given the combination of expanded contribution limits, short-term tax breaks, and potential long-term complexity, financial advisors recommend:
- Maxing out contributions in 2025, especially if age 50+
- Reviewing Roth strategies before potential RMD rules shift
- Adjusting Social Security tax projections
- Consulting estate planners to take advantage of the 2026 exemption increase
- Re-evaluating long-term care plans in light of Medicaid changes
Key takeaways
- IRS raises 401(k) contribution limits to $23,500 for 2025
- Catch-up contributions allow workers 60–63 to save up to $34,750
- The Big Beautiful Bill introduces major tax planning changes for older adults
- Roth IRA RMDs and Social Security tax rules could change
- Medicaid cuts and expiring deductions create long-term uncertainty
More
Make FL1 part of your day.
Local reporting. Useful updates. More ways to stay close to your community.
Go ad-free
Support independent local reporting and enjoy FL1 without display ads.
$4.99 / month
Become a member →Cancel anytime. Third-party media players may contain ads.Get the daily briefing
Start your morning with the headlines that matter across the Finger Lakes.
Find more FL1 on Google
Choose FingerLakes1.com as a preferred source to see more of our reporting in your Google news results.

This content is brought to you by the FingerLakes1.com Team. Support our mission by visiting www.patreon.com/fl1 or learn how you send us your local content here.